The EB-5 Immigrant Investor Program is approaching a consequential year. Investors are asking what happens after the 30 September 2026 grandfathering deadline, whether EB-5 will change in January 2027, and whether the Regional Center Program will continue beyond September 2027.
The short answer is that EB-5 is not scheduled to end in January 2027. However, the minimum investment amounts are scheduled to be adjusted for inflation from 1 January 2027. The Regional Center Program is separately authorised through 30 September 2027, when Congress will need to extend it or adopt replacement legislation if the program is to continue in its current form.
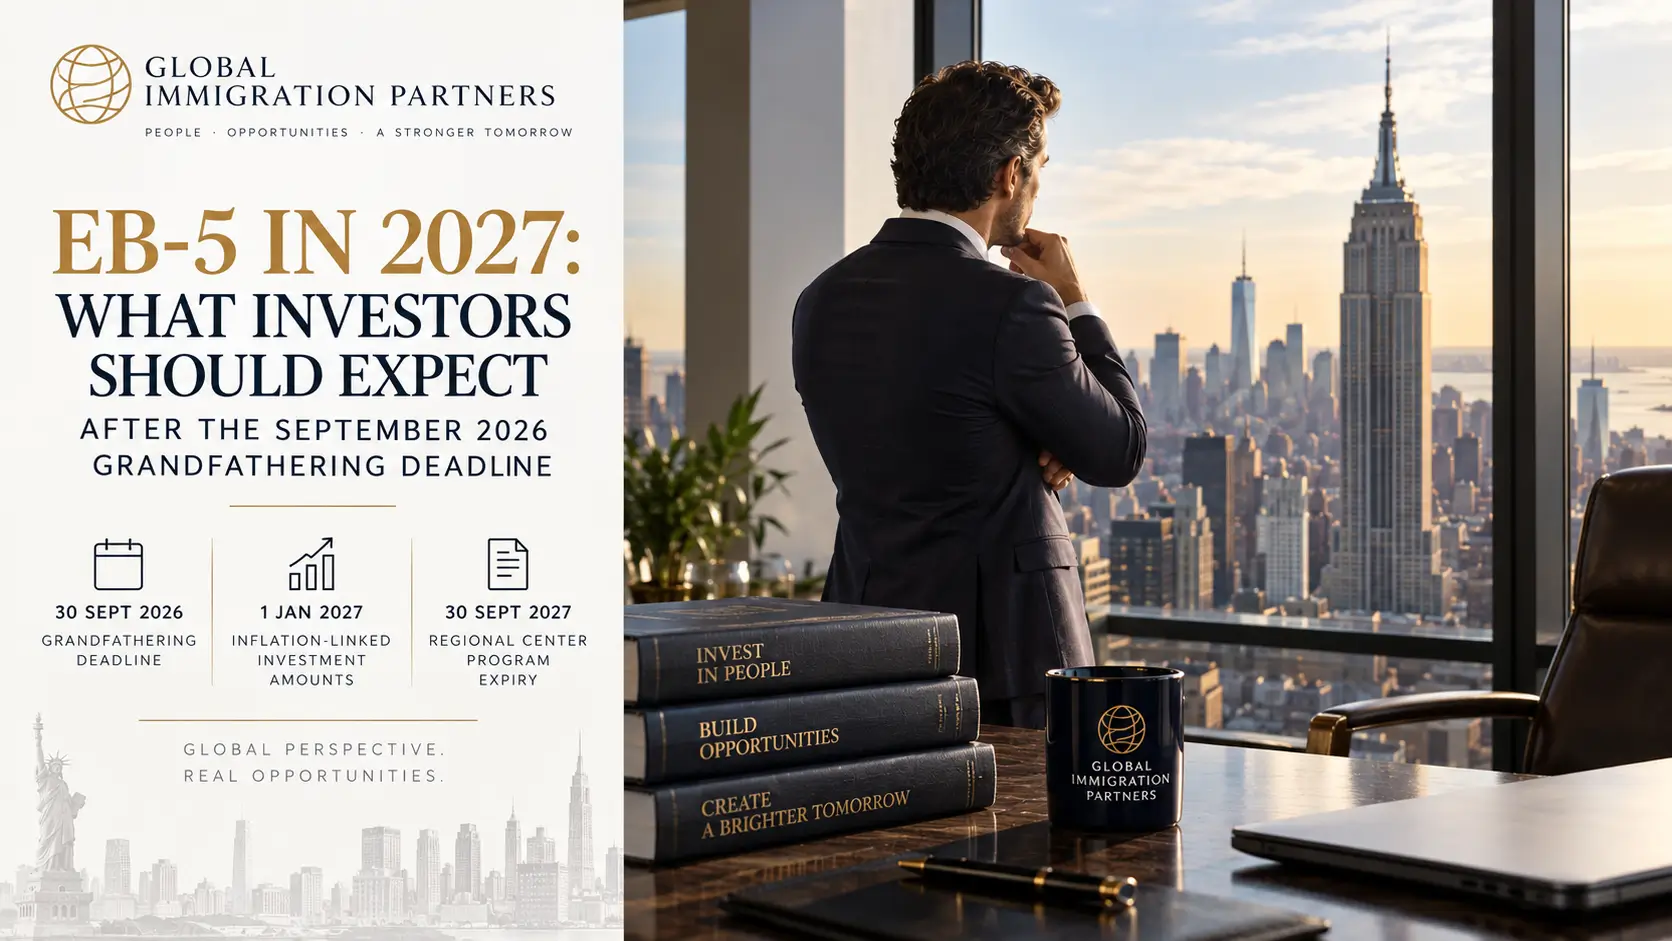
This creates three important dates:
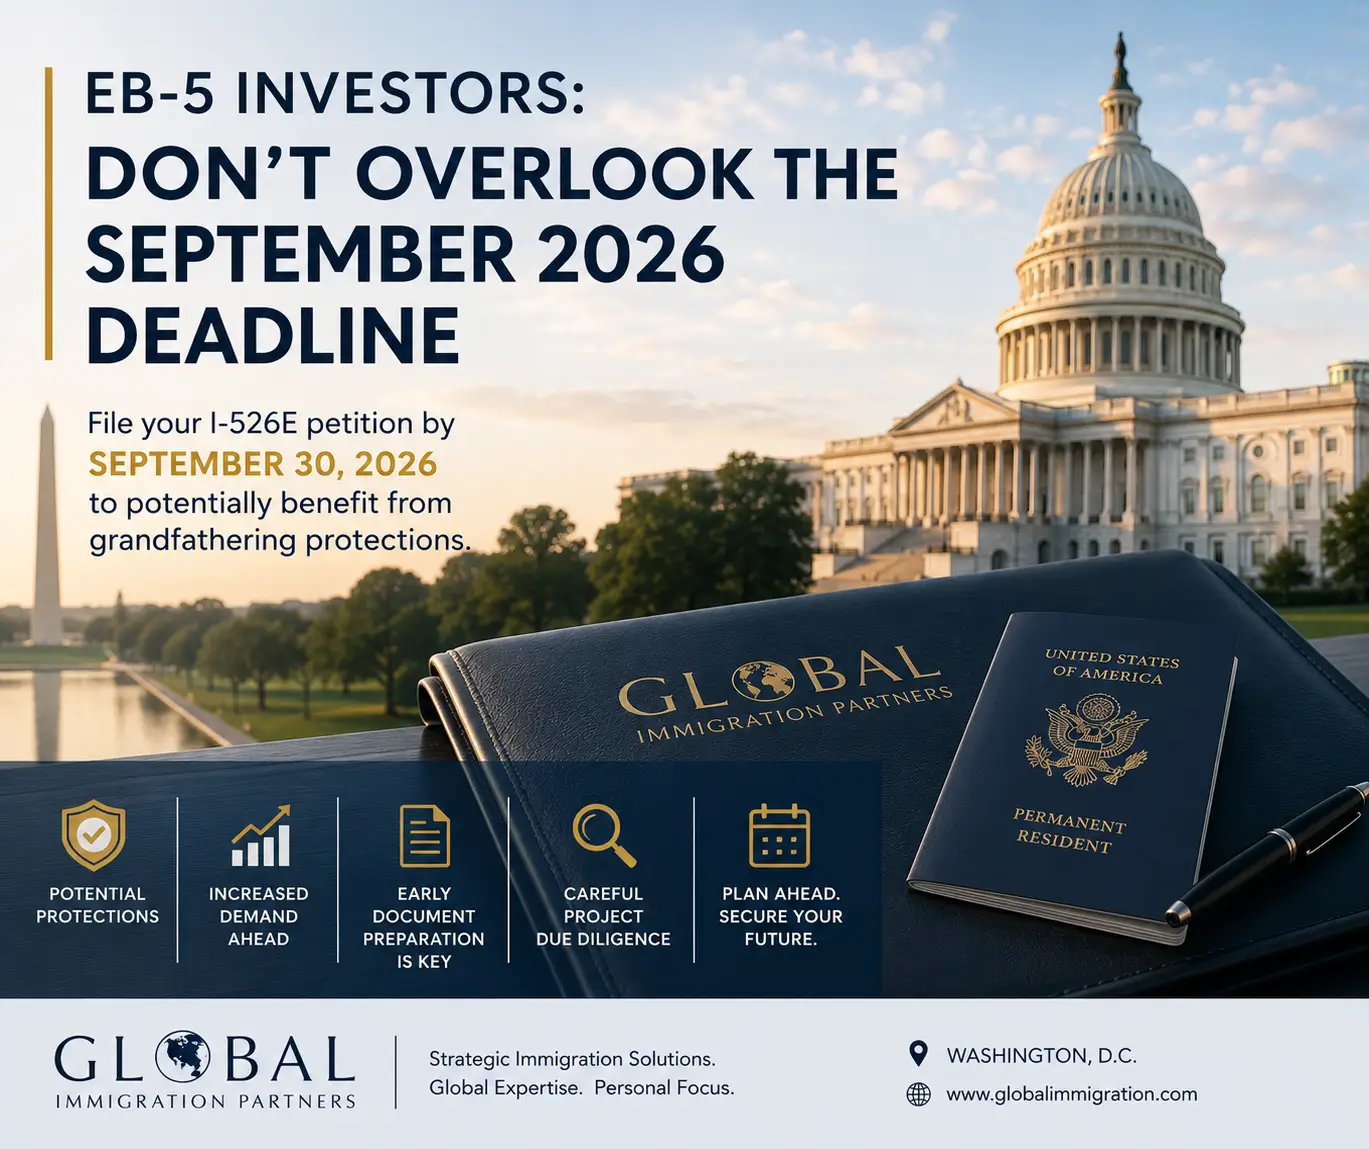
- 30 September 2026: the statutory grandfathering deadline for qualifying regional center petitions;
- 1 January 2027: the scheduled date for inflation-linked changes to the minimum investment amounts; and
- 30 September 2027: the current expiry date for the EB-5 Regional Center Program.
Investors should understand that these dates affect different rights and risks.
What is the EB-5 grandfathering deadline?
The EB-5 Reform and Integrity Act of 2022 reauthorised the Regional Center Program and introduced significant integrity, reporting and investor-protection measures. It also created an important protection for certain investors who file their Form I-526E petitions on or before 30 September 2026.
This protection is commonly called “grandfathering.” In broad terms, it directs the government to continue processing qualifying petitions filed by the deadline even if the Regional Center Program later expires. This is especially important because the program’s present authorisation ends on 30 September 2027.
Grandfathering does not mean that a petition will be approved automatically. An investor must still satisfy all EB-5 requirements, including lawful source and path of funds, the required qualifying investment, job creation and the other conditions applicable to the petition. It also does not guarantee immediate visa availability or protect an investor from ordinary adjudication issues.
Its central benefit is continuity: a qualifying investor should not lose the ability to have the case adjudicated merely because Congress later permits the Regional Center Program to lapse.
Can investors still file after 30 September 2026?
Yes. Unless the law changes, the Regional Center Program remains authorised until 30 September 2027. The September 2026 date is not the program’s expiration date.
However, a regional center investor filing after 30 September 2026 will not have the same statutory grandfathering protection. If Congress renews the program before its September 2027 sunset, that distinction may never become practically important. If Congress delays, substantially changes or does not renew the program, post-deadline investors may face greater uncertainty.
That does not necessarily mean that every petition filed after September 2026 would fail. The outcome would depend on the legislation then in force, any transition provisions enacted by Congress, USCIS policy and potentially litigation. It does mean that an investor filing after the deadline accepts a risk that is materially different from the risk faced by a protected pre-deadline filer.
Investors should also avoid treating 30 September as a target date for starting their case. Source-of-funds analysis can be document-intensive, particularly where capital comes from business income, property sales, gifts, loans, inheritance or funds transferred through several accounts or countries. Project selection, securities documents and the transfer of investment capital also require time.
What will happen to EB-5 in January 2027?
EB-5 is not currently scheduled to terminate in January 2027. The principal scheduled January change concerns the investment amounts.
The current minimum investment is $800,000 for an investment in a targeted employment area or qualifying infrastructure project and $1,050,000 for other EB-5 investments. Under the Reform and Integrity Act, these amounts are scheduled to adjust for inflation on 1 January 2027 and every five years thereafter.
The general investment amount is to be adjusted using the statutory inflation formula and rounded as required by law. The lower amount is then set at 75% of the adjusted general amount. The precise new figures should be confirmed from the official government announcement and implementing guidance before investors rely on them.
Accordingly, an investor filing in 2027 may need to contribute more capital than an investor filing under the present thresholds. Investors planning to file around the end of 2026 should obtain advice on which amount applies to their proposed filing and should not assume that signing project documents or transferring funds alone will secure the existing threshold.
January 2027 will also mark the start of a new Congress. That may accelerate debate about the future of EB-5, but a new Congress does not itself cancel or renew the program. Any material statutory change would require legislation.
Our EB-5 forecast for 2027
No one can guarantee what Congress or USCIS will do. Based on the present statutory framework, several developments are more likely than others.
1. Higher minimum investment amounts
The most predictable change is an increase in the required capital from January 2027. The amount will depend on the statutory calculation and the government’s implementation.
This may produce increased filing activity in late 2026 as investors seek to proceed before the adjustment. Investors should wait for official confirmation of the new amounts rather than rely on industry estimates.
2. Greater importance of the filing date
In 2027, investors will fall into materially different groups: those whose regional center petitions were filed by 30 September 2026 with statutory protection, and those who filed later without that protection.
This distinction is likely to become more important as the September 2027 sunset approaches. Post-September 2026 investors may need to pay particularly close attention to congressional negotiations and any proposed transition provisions.
3. A push for reauthorisation before September 2027
The Regional Center Program now operates under a substantially more regulated structure than it did before the 2022 reforms. Regional centers, developers, investors and economic-development stakeholders are likely to press Congress for a further extension.
Renewal is plausible, but it should not be treated as guaranteed. Congress could pass a straightforward extension, attach EB-5 to broader legislation, make targeted amendments, or allow negotiations to continue close to the deadline. A temporary lapse is also possible if legislation is delayed.
4. Possible changes to reserved-visa rules and investment incentives
The 2022 law reserves portions of annual EB-5 visas for rural projects, high-unemployment areas and infrastructure projects. Rural projects also receive priority processing under the statute. These provisions have significantly shaped project selection and investor demand.
Congress may leave the structure unchanged, or it could revisit how reserved visas, targeted employment areas, job creation and project eligibility operate. Proposals affecting affordable housing, infrastructure or other policy priorities may also enter the debate.
Until legislation is enacted, however, these possibilities remain forecasts rather than law.
5. Increased visa-availability pressure
Demand from high-volume countries could lead to longer waits and the introduction or movement of cut-off dates in reserved or unreserved categories.
An approved I-526E petition does not by itself guarantee that an immigrant visa is immediately available. Country of birth, petition category and priority date can materially affect timing.
Investors from countries with high demand should consider visa availability alongside project quality and source-of-funds preparation. Choosing a rural project solely because a reserved category is currently available may be shortsighted if the project itself is unsuitable or immigration demand later changes.
6. Continued USCIS scrutiny and compliance enforcement
The integrity provisions introduced in 2022 were designed to increase transparency, oversight and accountability.
In 2027, investors should expect continued attention to regional center compliance, promoter disclosures, fund administration, project documentation, job-creation methodology and the lawful source and path of investment funds.
Strong legal preparation will remain important. A project’s association with a regional center does not mean that USCIS has guaranteed the investment, approved its financial merits or removed the possibility of loss.
What happens if Congress does not renew the Regional Center Program?
If Congress takes no action, the Regional Center Program’s current authorisation is scheduled to end after 30 September 2027.
That would not necessarily end every part of EB-5. The direct EB-5 category has a different statutory basis, although it normally requires the investor’s enterprise to create the qualifying jobs directly and is structurally different from a regional center investment.
For regional center cases, investors who properly filed by 30 September 2026 would have the strongest statutory continuity protection. Investors who filed after that date could face uncertainty unless Congress includes additional protections in new legislation or the government adopts a legally sustainable transition position.
Historically, Congress has sometimes renewed immigration programs late or through short-term extensions. Investors should therefore prepare for several possible outcomes rather than assume either seamless renewal or permanent termination.
Should investors wait until 2027?
Waiting may carry three separate risks:
- Loss of statutory grandfathering protection;
- A higher minimum investment amount; and
- Less time before the Regional Center Program’s current sunset date.
That does not mean every prospective investor should rush into an unsuitable project or submit an incomplete petition. EB-5 capital must remain at risk, and immigration success and financial performance are separate questions.
Investors should complete independent financial and securities due diligence in addition to obtaining immigration advice.
For an investor who is already considering EB-5, the more prudent approach is to begin eligibility and source-of-funds planning early. This allows time to identify documentary gaps, compare appropriate projects and make an informed decision before a deadline dictates the strategy.
The outlook for EB-5 in 2027
The most likely 2027 picture is not the sudden disappearance of EB-5 in January. It is a year of higher investment thresholds, closer attention to filing dates, growing visa-demand pressures and increasingly active negotiations over the Regional Center Program’s future.
The critical message is straightforward: 30 September 2026, 1 January 2027 and 30 September 2027 are separate legal milestones. Investors who understand the difference will be better positioned to manage both immigration and investment risk.
Global Immigration Partners PLLC advises EB-5 investors on eligibility, lawful source and path of funds, project-related immigration issues, I-526E petitions, adjustment of status, consular processing and removal of conditions. Because the law, Visa Bulletin and government guidance can change, investors should obtain advice based on the rules in effect at the time of filing.
This article is for general information only and does not constitute legal, tax, securities or investment advice. Past outcomes do not guarantee future results.